
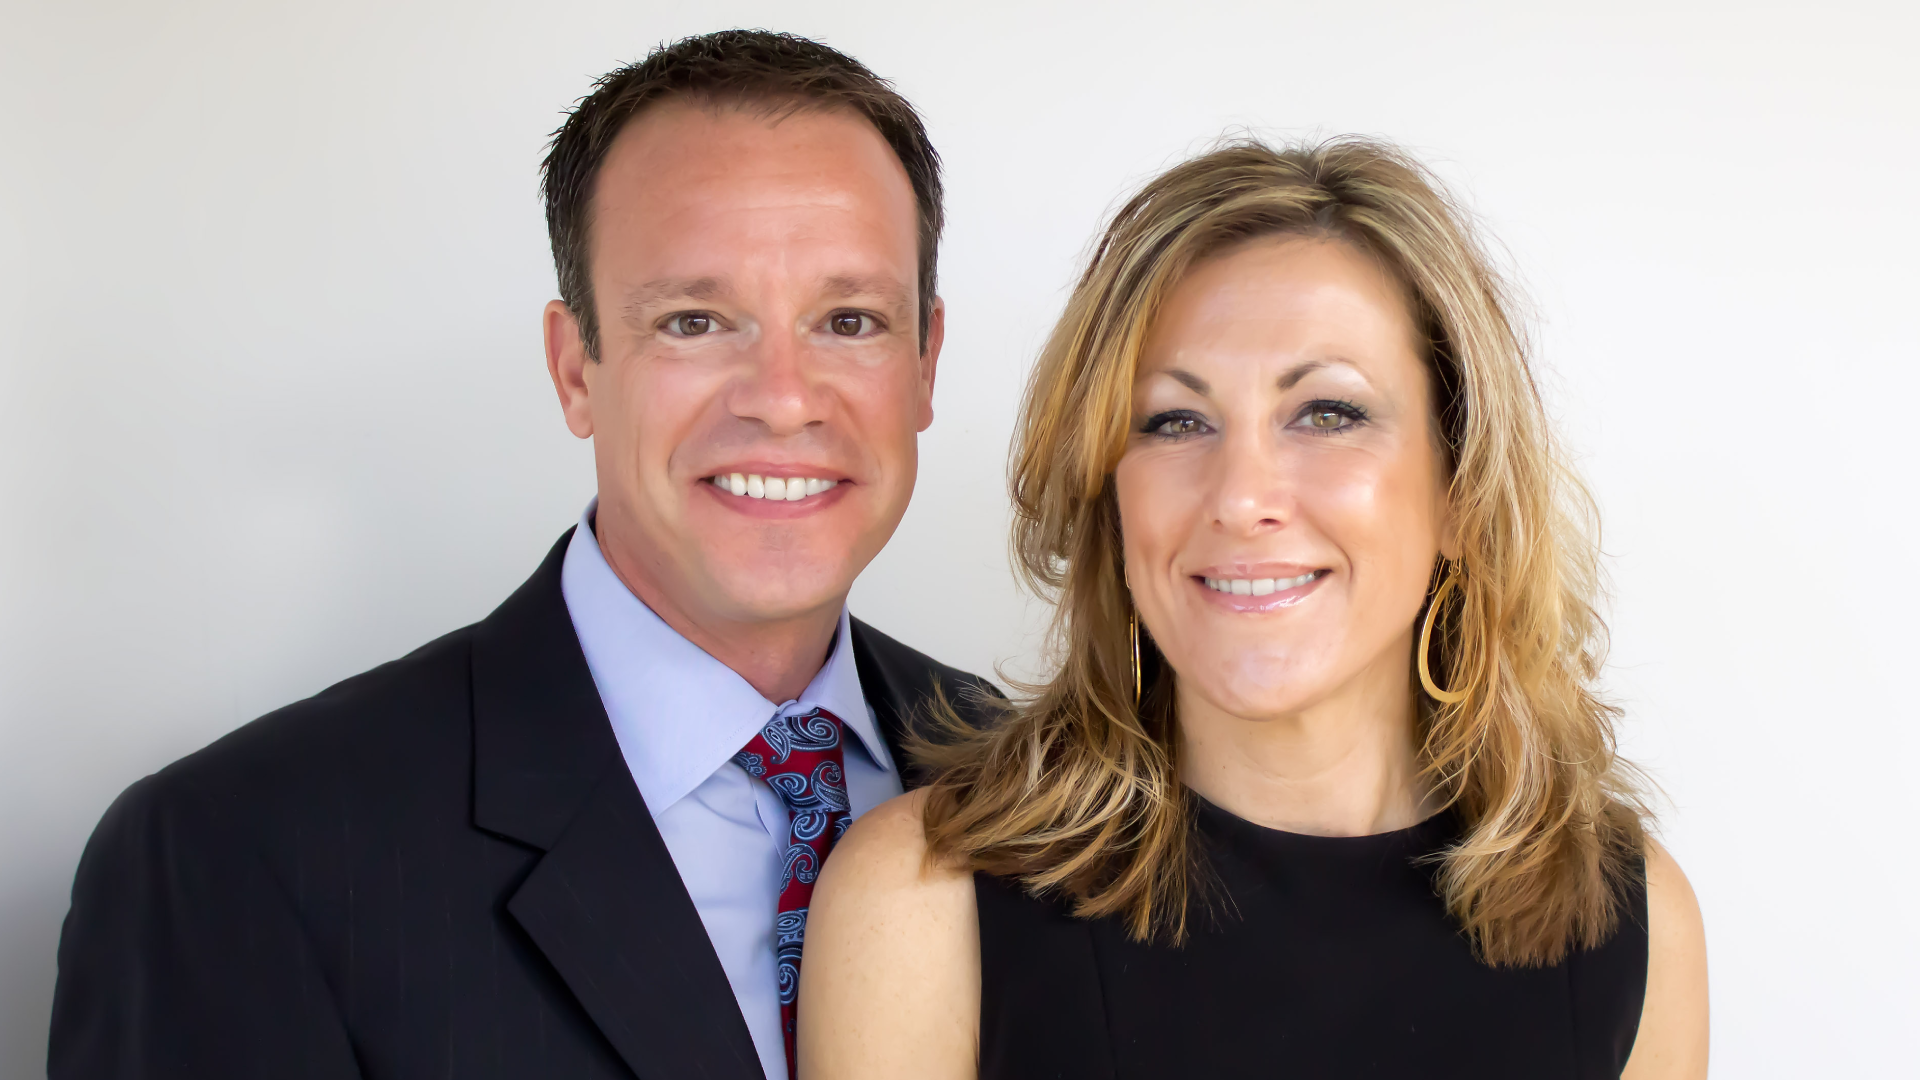
JEHM Retirement Advisors on Where to Get the Right Advice
Growth—it’s the obvious aim for anyone with investment accounts. To achieve it, many look for expert recommendations on where to put their money, but is there ever a time when growth isn’t the primary goal?
According to Eric and Jennifer Lahaie, founders of JEHM Wealth & Retirement, the perspective of someone 20 years from retirement should be vastly different than that of someone five years from retirement. As the outlook changes, so might the type of counsel a person seeks within the nuanced industry of financial planning.
“When you’re working, your investments have one job—and that’s to grow,” Eric says. During that time, investment advisors may be valuable allies. Closer to retirement, however, a retirement advisor can maximize wealth built throughout a career.
“When your lifestyle is connected to a paycheck, you’re not so worried about how your 401k is doing because historically, the market has trended upward,” Jennifer says. “After retirement, there’s a strong emotional reaction to a big fluctuation.”
The Lahaies, who have earned the Retirement Income Certified Professional (RICP®) designation, contrast investment advising to their specialty, retirement planning, which focuses more on utilization than growth. Ideally, clients will engage them five years prior to retirement or within the first five years afterward, a crucial time to convert accounts and to understand the tax implications of pulling funds from various sources.
“We move from investment growth alone to preservation, distribution, and growth,” Jennifer says.

Eric notes that investors tend to think financial advisors can move money in and out of the market so they’ll never lose anything (this is commonly known as “market timing”), and their account value will only go up, yet the “biggest money managers in the industry” openly say no one can consistently predict what the market will do, how long a trend will last, and how regulatory components will impact outcomes.
“With that mindset, investors are extremely reactive,” Eric says. “In retirement, small adjustments are everything.”
Retirement planning might be somewhat unclear because retirement itself wasn’t the norm until the latter half of the 20th century. The term “401k” didn’t become part of the American vocabulary until the late 1970s.
“Currency has been around since 600 BC, but the idea of living for decades after you stop working is still relatively new,” Eric says.
Jennifer states that most investment advisors start with tools of the trade—stocks, bonds and mutual funds— while retirement advisors start with goals, helping clients define their vision of a meaningful life after retirement.
“We know life can be unpredictable,” Jennifer says. “A good retirement advisor not only considers all the factors we cover with our clients, but also plans for the times when things don’t go as planned.”

jehmwealth.com | 864.527.0482
117 Woodruff Place Circle, Suite A, Simpsonville, SC 29681


